The Hidden Cost of Retirement: How Healthcare Expenses Are Eroding Social Security Income

For many retirees, the biggest threat to their financial security isn't market volatility or inflation alone. It's the growing share of retirement income consumed by healthcare expenses.
Financial advisors spend considerable time helping clients determine how much income they'll need in retirement. They evaluate Social Security benefits, investment portfolios, withdrawal strategies, and income replacement ratios. But an important question often receives less attention: How much of that income will actually remain after paying for healthcare?
The answer may surprise both advisors and their clients.
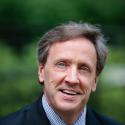
In a recent Financial Experts Network webinar, How Healthcare Costs Quietly Erode Retirement Income, Matt Rutledge, Professor of the Practice in the Economics Department at Boston College and Research Fellow at the Center for Retirement Research at Boston College, presented research examining the impact of out-of-pocket medical expenses on retirees' purchasing power.
His findings reveal that even with Medicare coverage, healthcare expenses consume a significant portion of retirement income, leaving some older Americans with surprisingly little money for everyday living expenses.
Nearly 30% of Social Security Income Goes Toward Healthcare
One of the most striking findings from Rutledge's research is that the median household retains just 71% of its Social Security income after paying out-of-pocket medical expenses.
That means approximately 29% of Social Security benefits are effectively consumed by healthcare costs before retirees can spend those benefits on housing, groceries, transportation, or other necessities.
For some households, the situation is considerably worse.
The research found that approximately one-quarter of households spend more than half of their Social Security benefits on healthcare. Among households facing the greatest burden relative to their benefits, medical expenses consume approximately 98% of Social Security income.
Consider a retiree receiving $2,500 per month in Social Security benefits. If healthcare consumes 29% of that income, approximately $725 goes toward medical expenses, leaving just $1,775 for everything else.
And for retirees who depend almost entirely on Social Security, that reduction can have serious consequences.
"One of the most important questions in retirement planning isn't simply how much income a client receives, but how much remains after essential expenses are paid."
Medicare Doesn't Eliminate Healthcare Costs
Many clients assume that once they reach age 65 and enroll in Medicare, most of their healthcare expenses will be covered.
While Medicare provides essential financial protection, it doesn't eliminate out-of-pocket costs.
Rutledge's research included Medicare premiums, deductibles, copayments, coinsurance, prescription drugs, and services not fully covered by insurance, such as certain dental, vision, and hearing expenses.
These costs can accumulate quickly, particularly for retirees managing chronic medical conditions or requiring frequent treatment.
The study also found an important difference between predictable and unpredictable healthcare expenses.
For retirees with relatively low medical spending, insurance premiums represented a substantial share of their annual healthcare costs. Although these expenses can be significant, they are generally easier to incorporate into a budget.
For retirees with higher medical spending, a larger share came from less predictable expenses, including hospitalizations, medical procedures, and other out-of-pocket charges.
This distinction matters because even a well-constructed retirement budget can be disrupted by unexpected medical needs.
And importantly, the research excluded long-term care expenses, meaning the potential financial exposure could be even greater for clients who eventually require extended care.
Some Retirees Face a Much Greater Financial Burden
Healthcare expenses don't affect every retiree equally.
Rutledge's research identified several groups that experience particularly significant financial pressure.
Women: Women generally have a smaller percentage of retirement income remaining after healthcare expenses than men. Longer life expectancy may contribute to this difference, although other factors can also influence spending.
Retirees in poor health: Individuals with chronic conditions or limitations in daily activities often face greater medical expenses and less financial flexibility.
Lower-income retirees: Households with limited retirement savings or pension income are especially vulnerable because healthcare consumes a larger percentage of their available resources.
Retirees without Medicaid coverage: Medicaid can provide substantial financial protection for eligible low-income beneficiaries. However, individuals who don't qualify may face significant out-of-pocket costs despite having relatively modest incomes.
For financial advisors, these findings reinforce the importance of tailoring healthcare planning to each client's financial circumstances, health status, and available resources.
Does Medicare Advantage Really Save Retirees Money?
With Medicare Advantage enrollment continuing to grow, many retirees are attracted to plans offering low or zero additional monthly premiums, prescription drug coverage, and benefits such as dental, vision, or hearing services.
But do these plans actually leave retirees with more money?
Rutledge's research found that Medicare Advantage enrollees had outcomes broadly similar to those in the study's Medicare-only comparison group when measuring how much Social Security income remained after medical expenses.
That doesn't mean Medicare Advantage is necessarily a poor choice. Nor does it establish that traditional Medicare is always better.
Rather, it highlights why advisors and their clients should look beyond advertised premiums when comparing coverage.
A plan with a low monthly premium may still involve significant copayments, coinsurance, network restrictions, or other limitations when a beneficiary needs substantial medical care.
The webinar also raised an important issue regarding the ability to switch coverage later in retirement.
Clients who initially choose Medicare Advantage may encounter medical underwriting requirements when seeking Medigap coverage in subsequent years, depending on applicable state rules and enrollment protections.
That makes Medicare coverage decisions especially important for clients who want flexibility as their healthcare needs evolve.
Why Haven't Healthcare Reforms Reduced the Overall Burden?
Over the past two decades, Medicare has undergone substantial changes intended to expand coverage and reduce costs.
The introduction of Medicare Part D expanded prescription drug coverage, while subsequent reforms gradually eliminated the original Part D coverage gap.
More recently, the Inflation Reduction Act introduced additional protections, including limits on certain prescription drug costs and an annual cap on covered Part D out-of-pocket spending.
Yet Rutledge's research found relatively little change in retirees' overall healthcare spending burden across the 2018, 2020, and 2022 study periods.
One possible explanation is that prescription drugs represent only part of the total healthcare expense picture.
Hospitalizations, physician services, insurance premiums, medical devices, and uncovered services continue to create significant financial obligations.
Rutledge also emphasized that the research data ended in 2022, before several newer prescription drug reforms took effect.
Future studies will be needed to determine whether those changes meaningfully improve retirees' purchasing power.
What This Means for Financial Advisors
The research offers an important reminder that traditional retirement income calculations may not tell the whole story.
A client may appear financially prepared based on projected Social Security benefits, investment income, and withdrawal rates. But those projections can overstate available spending power if healthcare costs aren't adequately considered.
Financial advisors can help clients prepare by incorporating several strategies into their planning process.
1. Evaluate Retirement Income After Healthcare Expenses
Rather than focusing exclusively on gross retirement income, advisors should estimate how much income clients will retain after Medicare premiums, cost sharing, and other expected medical expenses.
2. Stress-Test Healthcare Spending
Retirement projections should consider scenarios involving higher medical expenses, chronic illness, and unexpected hospitalizations.
Clients may need additional liquidity or flexibility to manage periods of elevated spending.
3. Review Medicare Coverage Annually
Medicare coverage decisions should account for total potential costs, provider networks, prescription drug coverage, and access to necessary care—not simply monthly premiums.
4. Consider the Impact of IRMAA
Higher-income retirees may pay additional Medicare Part B and Part D premiums through income-related monthly adjustment amounts.
Advisors should consider how Roth conversions, capital gains, retirement-account withdrawals, and other income decisions may affect future Medicare premiums.
5. Plan Separately for Long-Term Care
Because Rutledge's research excluded long-term care expenses, advisors should address this potentially significant financial risk separately.
Long-term care planning may involve insurance, dedicated savings, family support considerations, or other strategies appropriate to the client's circumstances.
The Bigger Picture: Retirement Income Isn't the Same as Retirement Spending Power
Perhaps the most important lesson from Rutledge's research is that retirement income adequacy cannot be measured solely by the size of a Social Security check or investment portfolio.
For the median household, healthcare expenses consume nearly 30% of Social Security income. For approximately one-quarter of households, they consume more than half.
And despite years of healthcare policy changes, the overall burden remained relatively stable through the study's latest available data.
For financial advisors, this creates an opportunity to strengthen retirement planning conversations by helping clients understand the difference between income received and income available to spend.
The bottom line: A successful retirement plan shouldn't simply answer the question, "Will my clients have enough income?" It should also address, "How much of that income will they actually have left after healthcare expenses?"
Understanding that distinction can help advisors build more realistic retirement projections, identify financial vulnerabilities, and prepare clients for the healthcare costs that may quietly erode their financial security.
About the Webinar
How Healthcare Costs Quietly Erode Retirement Income was presented by Financial Experts Network on November 11, 2026, featuring Matt Rutledge, Professor of the Practice at Boston College and Research Fellow at the Center for Retirement Research at Boston College.
The presentation examined research using the Health and Retirement Study to measure how out-of-pocket healthcare expenses affect Social Security benefits and overall retirement purchasing power.
Financial Experts Network provides continuing education webinars and on-demand educational programs for financial advisors and other financial professionals.
Visit FinancialExpertsNetwork.com to explore upcoming webinars, educational resources, and membership opportunities.
Disclaimer: This article is intended for educational purposes and is based on the research and discussion presented during the webinar. Findings reflect the study population and available research data through 2022. Individual healthcare expenses and Medicare coverage vary. This article does not constitute individualized financial, tax, medical, or insurance advice.
Continue learning with our latest financial expert sessions
Explore upcoming webinars, gain industry insights, and stay ahead with expert-led education.
Explore Webinars